

Are camping pods “buildings” for capital allowances purposes?
The First-tier Tribunal (FTT) recently considered whether a number of camping pods could qualify for the annual investment allowance. As with many similar cases, the answer was “it depends”. What can you learn from it?
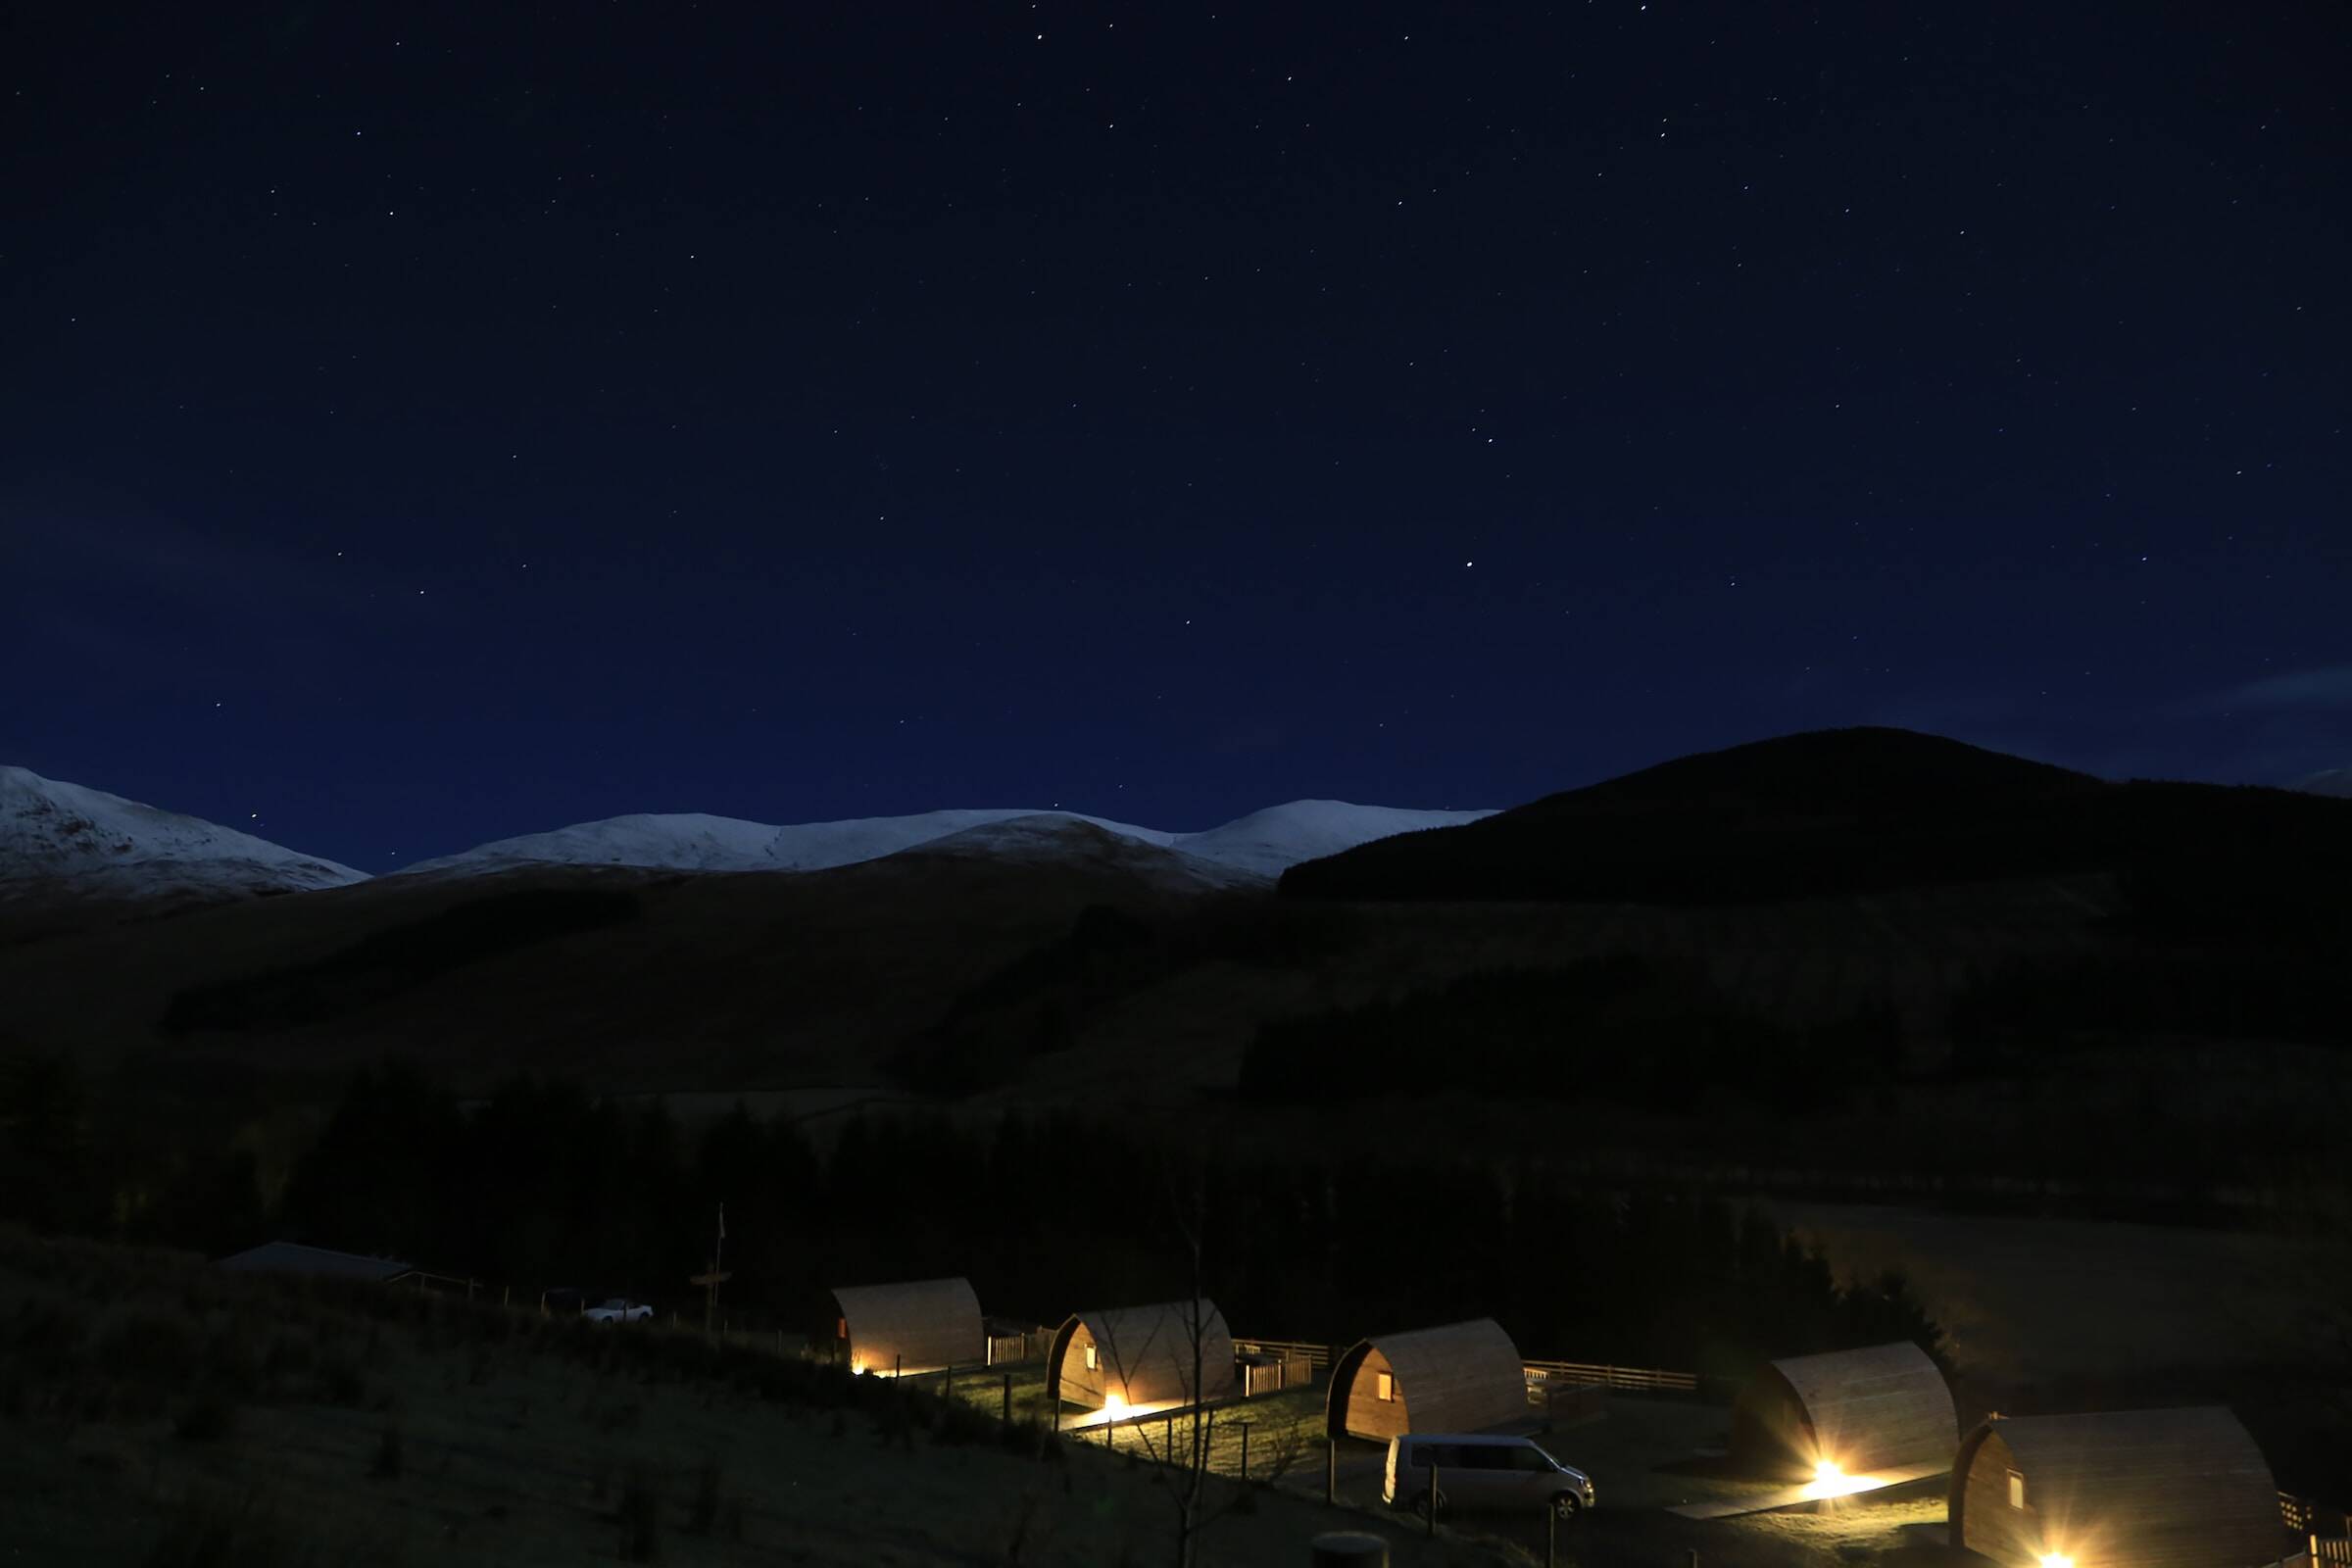
The company, Acorn Venture Ltd (AV), purchased 26 camping pods to provide accommodation for school children and teachers on residential trips. The cost of the pods was approximately £272,000. AV claimed capital allowances under the annual investment allowance on its tax return. The overall position was a loss. However, upon enquiry HMRC disallowed the claim on the basis that the pods were buildings or fixed structures.
At the hearing, the FTT made a distinction between the two types of pod included in the claim. There were 20 “basic” pods, and six more developed pods the FTT designated “teacher” pods. The basic pods were anchored to the ground to prevent movement, e.g. in windy weather. The pods were not living accommodation. At best, it could be said that they offered a similar function to a tent. The FTT determined that these basic pods were not fixed structures, and allowances could be claimed in respect of their cost. In contrast, the six teacher pods had flushing toilets, washing facilities and a kitchen area. The plumbing fixtures meant that the pods had to be secured to the ground with a greater degree of permanence than the basic pods. They were held to be fixed structures, so allowances couldn’t be claimed in respect of these pods.
This just goes to show how the devil is often in the detail with capital allowances. The two types of pod looked identical from the outside, but the internal features made the teacher pods more akin to living accommodation than a temporary shelter.
Related Topics
-
Payment deadline for corporation tax
-
HMRC targets undeclared consultancy income in the medical sector
HMRC is writing to people working in the medical sector where information supplied by private healthcare providers suggests that consultancy fees may have been omitted from their tax returns. Recipients have 30 days to check their position and respond. What should you do if you get a letter?
-
MONTHLY FOCUS: BUSINESS AND AGRICULTURAL PROPERTY RELIEF: WHAT DO THE NEW IHT RULES MEAN FOR YOU?
The inheritance tax treatment of businesses and farms changed fundamentally from 6 April 2026. The amount that can qualify for 100% business property relief and agricultural property relief is now capped, potentially leaving families with a significant tax bill for the first time. What has changed, and what should business owners and farmers be doing about it?




 This website uses both its own and third-party cookies to analyze our services and navigation on our website in order to improve its contents (analytical purposes: measure visits and sources of web traffic). The legal basis is the consent of the user, except in the case of basic cookies, which are essential to navigate this website.